What is the scope and market size of the Post-Mergers And Acquisitions (M&A) Integration Services Market?
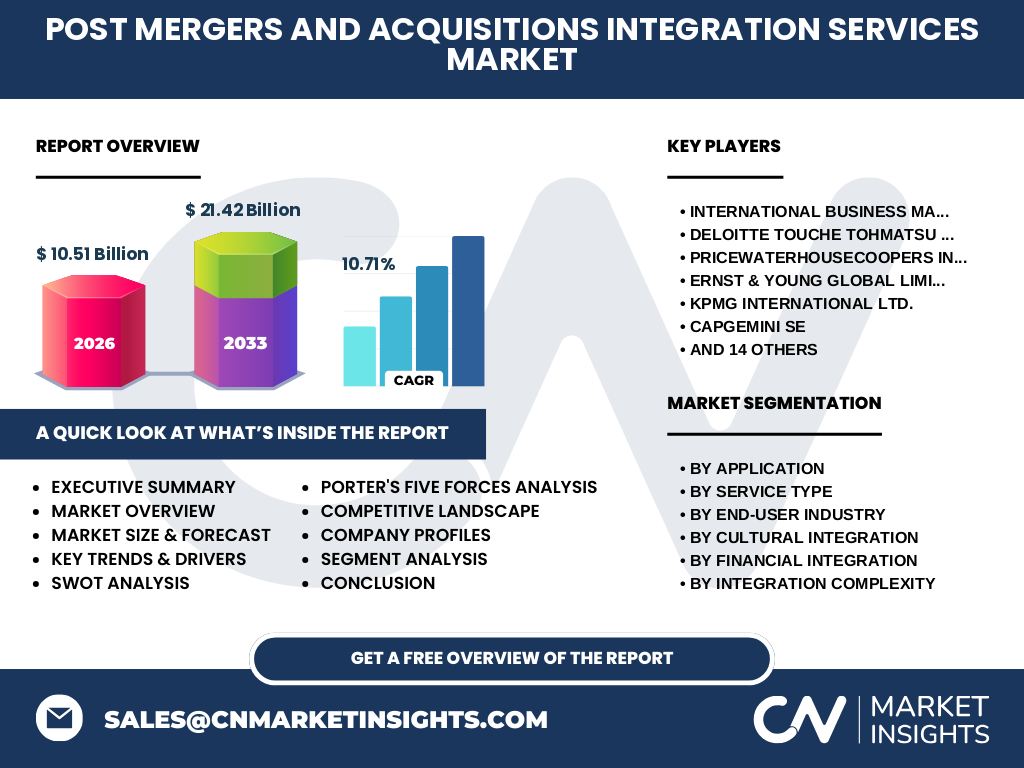
Our analysis indicates that the Post-Mergers And Acquisitions (M&A) Integration Services Market reached a valuation of 10.51 Billion in 2026. This specialized sector encompasses strategic advisory, operational harmonization, and technological alignment required when corporate entities execute mergers, absorbing regulatory frameworks enforced by bodies like the FTC and European Commission.
Structural Growth Drivers and Market Restraints
The Post-Mergers And Acquisitions (M&A) Integration Services Market industry trends highlight a surge in cross-border deal-making and enterprise digital transformation. However, market growth faces restraints from macroeconomic volatility, stringent cross-border antitrust reviews, and logistical hurdles in aligning disparate supply chain networks across localized jurisdictions.
Emerging Trends in Corporate Deal Consolidation
The shift toward automated synergy tracking is redefining the Post-Mergers And Acquisitions (M&A) Integration Services Market analysis. Firms increasingly leverage specialized SaaS platforms like Midaxo Ltd. and Shibumi.com Inc. to accelerate enterprise resource planning (ERP) data migration and streamline post-close value realization.
How did the global pandemic impact the Post-Mergers And Acquisitions (M&A) Integration Services Market?
Based on our research, COVID-19 initially delayed deal pipelines, but the subsequent recovery triggered a massive wave of distressed asset consolidation. This accelerated the demand for rapid IT infrastructure optimization and remote-enabled cultural integration programs managed by advisory powerhouses.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high concentration among elite strategy houses and Big Four accounting firms. Entities such as PricewaterhouseCoopers International Limited (PwC), Deloitte Touche Tohmatsu Limited, and McKinsey & Company Inc. dominate by offering comprehensive end-to-end execution capabilities from synergy valuation to tax and treasury integration.
Executive Summary of Post-Mergers And Acquisitions (M&A) Integration Services Market
This proprietary overview reveals robust expansion driven by complex industrial consolidation. Key findings emphasize that success in the Post-Mergers And Acquisitions (M&A) Integration Services Market relies heavily on mitigating human capital attrition and executing seamless IT architecture unification.
Market Forecast and Long-Term Projections (2027 to 2033)
Our data forecasts that the Post-Mergers And Acquisitions (M&A) Integration Services Market size will expand from 2027 to 2033 to reach an impressive 21.42 Billion, advancing at a robust CAGR of 10.71%. This trajectory reflects increasing corporate reliance on external transformation partners.
Segmentation Analysis Across Service Types and End-Users
The Post-Mergers And Acquisitions (M&A) Integration Services Market market size breaks down by application into Small And Medium Enterprises and Large Enterprise. Service types span Integration Strategy Development, Operational Integration, IT Systems Integration, Financial Integration, Cultural Integration, Human Resources, Supply Chain, and Regulatory Compliance.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with North America leading due to active private equity deal flow. Meanwhile, the Asia-Pacific region demonstrates the fastest growth, propelled by cross-border acquisitions in manufacturing and telecommunications requiring localized regulatory navigation.
In-Depth Regional Review of North America and Europe
North America anchors global demand within the Post-Mergers And Acquisitions (M&A) Integration Services Market due to deep capital markets and aggressive tech sector buyouts. Europe follows closely, driven by stringent data privacy laws like GDPR that necessitate specialized compliance and risk management advisory.
Company Profiles and Market Positioning
Industry leaders like Ernst & Young Global Limited (EY), KPMG International Ltd., and Bain & Company Inc. utilize proprietary frameworks to optimize supplier base rationalization and leadership alignment workshops, capturing substantial market share across complex enterprise mergers.
Porter's Five Forces Analysis of the Integration Sector
Our analysis indicates moderate-to-high competitive rivalry within the Post-Mergers And Acquisitions (M&A) Integration Services Market. While buyer power is balanced by the critical need for specialized expertise, threat of new entrants remains low due to high reputational barriers and proprietary methodology requirements.
SWOT Analysis of Post-Mergers And Acquisitions (M&A) Integration Services Market
Strengths include deep multidisciplinary expertise and advanced synergy valuation tools. Weaknesses involve high advisory fees. Opportunities lie in emerging AI-driven due diligence platforms, while threats stem from potential global recessionary pressures curtailing corporate deal volumes.
Value Chain Analysis from Strategy Formulation to Value Realization
The value chain flows from initial deal sourcing and synergy identification to granular operational execution. Specialized firms add value by harmonizing chart of accounts standardization, managing employee retention planning, and ensuring seamless supply chain risk mitigation.
Strategic Investment Insights and High-Potential Areas
Investors should target niche providers specializing in IT infrastructure optimization and cybersecurity alignment. As digital threats multiply during corporate consolidation, buyers increasingly prioritize firms capable of safeguarding proprietary data assets post-merger.
Conclusion and Key Takeaways for Industry Stakeholders
The Post-Mergers And Acquisitions (M&A) Integration Services Market represents a critical growth frontier for corporate advisory firms. Achieving synergy targets requires equal focus on hard systems integration and soft cultural change management programs.
Rigorous Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining global trade registry filings, primary executive interviews with M&A partners, and secondary macroeconomic indicators regarding cross-border capital flows and corporate restructuring indexes.
Scope of the Report and Coverage Parameters
This report covers global integration services across major sectors including healthcare, retail, financial services, and energy. Limitations exclude internal, in-house corporate restructuring initiatives lacking third-party advisory engagements.
Recent Developments, Partnerships, and Strategic Moves
Recent developments in the Post-Mergers And Acquisitions (M&A) Integration Services Market industry trends show major players like Alvarez & Marsal Holdings LLC and FTI Consulting Inc. forming strategic alliances with enterprise software providers to automate digital carve-outs and post-merger compliance tracking.